Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
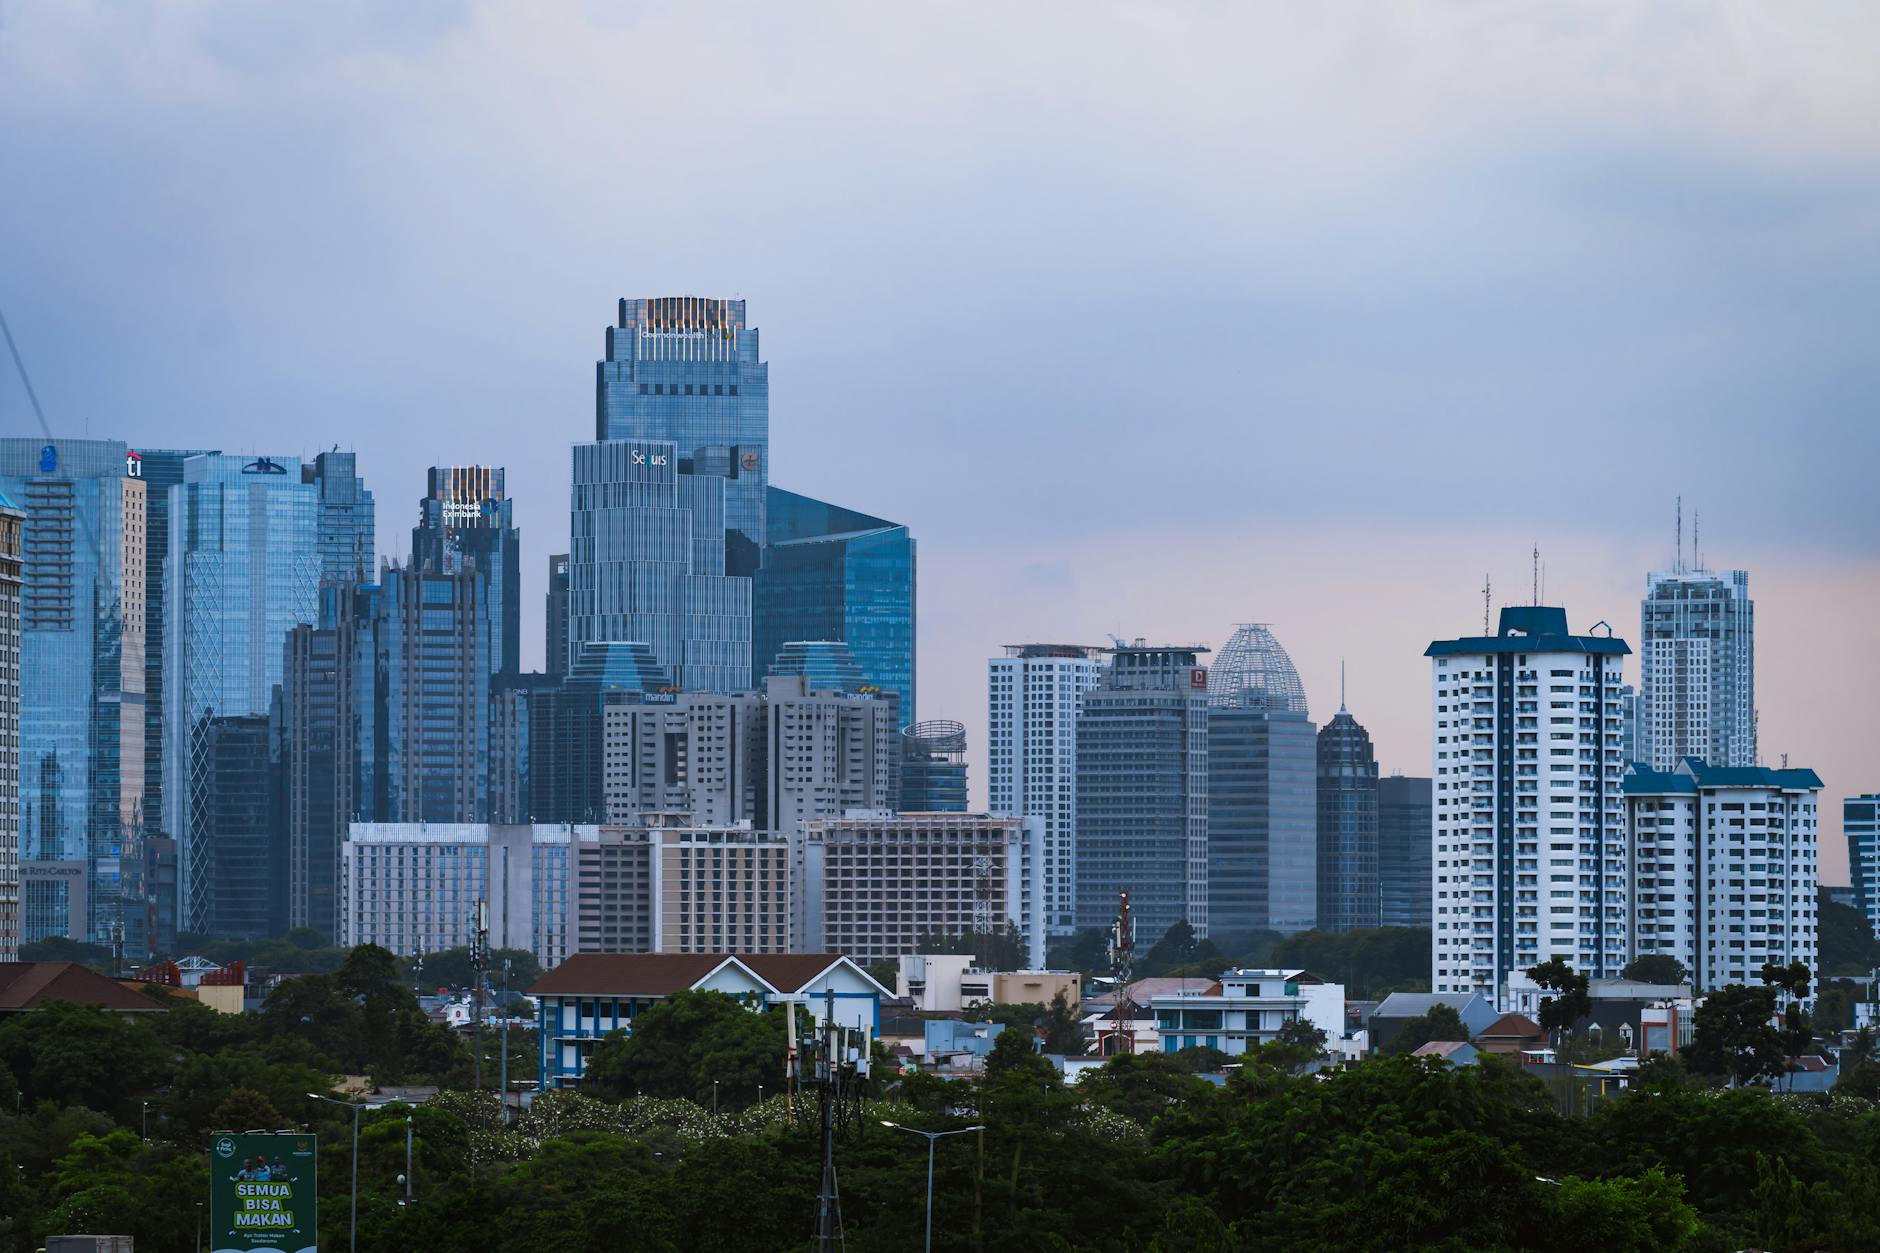
Indonesia faces a critical divergence in how international institutions assess its fiscal trajectory. While fundamentals remain stable, execution risks on major reforms—tax system modernization, energy projects, and state asset restructuring—are narrowing the margin for policy error.
Indonesia’s fiscal position presents a peculiar analytical challenge for policymakers and investors alike. The country is not experiencing a fiscal crisis in any conventional sense. Public debt remains moderate at approximately 40 percent of GDP, statutory fiscal deficit ceilings are enforced at 3 percent, and the macroeconomic fundamentals that underpin regional stability remain intact. Yet this apparent stability masks a critical divergence in how Indonesia’s economic trajectory is being assessed by major international institutions—a fracture that reveals as much about the country’s structural vulnerabilities as it does about the limitations of different analytical frameworks.
The divergence is not marginal. Between February and April 2024, Indonesia received fundamentally conflicting signals from the institutions that shape investor confidence and capital allocation decisions. This split assessment reflects a deeper question: whether Indonesia’s current policy direction can sustain its investment-grade status while executing an ambitious reform agenda that remains incomplete and exposed to significant execution risks.
Indonesia’s credit profile has fractured along institutional lines. Moody’s Investors Service and Fitch Ratings both revised Indonesia’s outlook from stable to negative in early 2024, signalling that while the country retains investment-grade status, the margin for policy error has contracted materially. This assessment reflects genuine concern about whether the current policy trajectory can be executed without placing pressure on Indonesia’s credit profile over a 12-24 month horizon.
In contrast, S&P Global Ratings has maintained a stable outlook, effectively signalling confidence that Indonesia’s long-standing fiscal discipline and macroeconomic management framework remain sufficient to sustain credit stability. This divergence is not semantic. It reflects different assessments of execution risk—Moody’s and Fitch are asking a downside question (what if reforms falter?), while S&P is asking a structural question (what if reforms succeed?).
The most consequential assessment, however, comes not from traditional rating agencies but from MSCI, the index provider. In January 2024, MSCI identified a structural liquidity problem in Indonesia’s equity market: concentration in a few large, tightly-held companies with limited free float. This assessment has real consequences. By constraining Indonesia’s index eligibility and weighting through accessibility criteria, MSCI has effectively limited a critical channel for portfolio capital inflows. For an economy structurally reliant on foreign portfolio flows, even marginal reductions in index accessibility translate into higher funding costs and reduced capital availability—a dynamic that can persist regardless of underlying fiscal fundamentals.
The International Monetary Fund and World Bank present a markedly more constructive assessment. Both institutions continue to characterize Indonesia as a relative outperformer among emerging markets, projecting steady growth, manageable inflation, and—critically—adherence to fiscal rules that many regional peers have abandoned. Recent IMF engagements in Washington have reinforced this view, with Indonesian policymakers emphasizing that existing fiscal and external buffers remain sufficient to weather near-term pressures.
This institutional optimism is not unfounded. Indonesia’s fiscal discipline over the past decade has been genuinely exceptional by emerging market standards. The country has maintained its statutory 3 percent fiscal deficit ceiling even during periods of external stress, a constraint that many ASEAN peers have suspended or violated. However, the multilateral assessment operates within a different analytical framework than the rating agencies and market indices. The IMF and World Bank are evaluating Indonesia’s medium-to-long-term structural trajectory. They are asking whether reforms, if executed successfully, can sustainably improve Indonesia’s fiscal position. Rating agencies and market indices, by contrast, are evaluating near-term execution risk and immediate market accessibility.
Indonesia’s fiscal strength ultimately depends on a single critical variable: tax base expansion. The country’s tax-to-GDP ratio stands at approximately 10 percent—substantially below regional peers like Thailand (15 percent), Malaysia (13 percent), and the Philippines (12 percent). This structural weakness is not accidental; it reflects both limited administrative capacity and a tax system that has remained largely unchanged for decades.
The government’s response—the CoreTax system—represents the most ambitious tax administration reform in recent decades. By integrating data systems, automating reporting, and reducing non-compliance, CoreTax is designed to lift Indonesia’s tax-to-GDP ratio to as high as 16 percent over a 5-10 year horizon. This would be transformational. An increase from 10 to 16 percent of GDP would add approximately $60-80 billion in annual revenue at current GDP levels, fundamentally altering Indonesia’s fiscal dynamics.
However, CoreTax remains in early implementation stages. While initial results are encouraging, the system has not yet demonstrated sustained revenue expansion. The risk is not technical failure—the system architecture is sound—but rather the political and administrative difficulty of sustained implementation across Indonesia’s sprawling bureaucracy. Tax compliance improvements of this magnitude require consistent enforcement, which remains a persistent challenge in the Indonesian context.
Indonesia’s fiscal outlook is also dependent on two parallel initiatives with fundamentally different risk profiles. First, a pipeline of major liquefied natural gas (LNG) projects—including ENI’s East Kalimantan Kutei developments, Mubadala’s South Andaman project, Inpex’s Masela project, and British Petroleum’s Tangguh Ubadari/CCUS initiative—could materially reshape Indonesia’s fiscal and external position. These projects are capital-intensive and multi-year in nature, with production timelines extending to 2028-2030. They will not provide short-term fiscal relief, but they could generate substantial revenue increases in the medium term.
More fundamentally transformative—and more risky—is Danantara, Indonesia’s new state investment fund. By consolidating state-owned enterprises into a single investment platform, the government is attempting to shift from a budget-constrained growth model toward one driven by asset optimization and improved capital allocation. In theory, this creates significant upside: higher returns on state assets, improved dividend flows to the budget, and stronger foreign investment participation.
In practice, Danantara introduces a new set of risks that rating agencies are right to scrutinize. The structure raises questions about transparency and oversight. More fundamentally, it risks blurring the boundary between sovereign and quasi-sovereign liabilities, creating contingent obligations that markets cannot fully price in advance. If Danantara’s structure lacks effective governance or becomes a vehicle for capital misallocation, it could generate hidden fiscal liabilities that emerge suddenly and disrupt market confidence.
Indonesia’s energy policy reveals a similar tension between policy ambition and execution clarity. The government is pursuing simultaneous transitions: biofuel expansion, electric vehicle adoption, and coal-based dimethyl ether (DME) development. Each initiative addresses the structural problem of import dependence, but they operate through different mechanisms and with different timelines. This creates implementation complexity and raises questions about resource prioritization and policy coherence.
The energy sector’s fiscal contribution also depends heavily on commodity prices. With global LNG prices volatile and oil prices subject to geopolitical shocks, Indonesia’s energy revenues remain structurally exposed to external price cycles. This exposure has historically created fiscal volatility, a dynamic that persists regardless of how efficiently energy resources are developed.
The divergence in Indonesia’s fiscal assessments ultimately reflects a fundamental disagreement about execution capacity, not about underlying fundamentals. Indonesia’s debt levels are manageable, its fiscal discipline has been exemplary, and its growth trajectory remains solid. The country is not at risk of a fiscal crisis in the conventional sense.
However, the rating agencies’ negative outlook and MSCI’s market accessibility concerns point to a real vulnerability: Indonesia’s fiscal improvement depends on sustained execution of complex, multi-year reforms (CoreTax, energy projects, Danantara restructuring) while maintaining market confidence. Any significant slippage in reform implementation—whether from political constraints, administrative capacity limitations, or external shocks—could trigger a rapid reassessment by market participants, particularly portfolio investors.
The multilateral institutions’ optimism is justified if reforms succeed. The rating agencies’ caution is justified if they falter. Indonesia’s fiscal future depends on which scenario materializes—and on whether the government can maintain investor confidence during the extended implementation period when reforms are underway but results are not yet visible.
Indonesia faces a critical 24-36 month window in which to demonstrate sustained reform execution. CoreTax must begin generating measurable revenue improvements. Energy projects must maintain their development timelines. Danantara must establish transparent governance and demonstrate effective asset management. Simultaneously, the government must maintain fiscal discipline and external communication to prevent a confidence shock.
The divergence in external assessments is unlikely to resolve until Indonesia demonstrates concrete progress on these fronts. Rating agencies will maintain their negative outlook until execution becomes visible. MSCI’s market accessibility constraints will persist until equity market structure improves. The multilaterals will maintain their optimism unless fundamentals deteriorate. Indonesia’s task is to convert policy ambition into demonstrable results before market confidence erodes further.